

Business Operation · 2025
In this section22 topics
- Corporate Information4 items
- Dividend Policy2 items
- Major Shareholders3 items
- Business Strategies Overview5 items
- Material Changes & Developments1 item
- Use of Proceeds from Securities Offerings1 item
- Commitments Made in the Registration Statement1 item
- Group Operating-Structure Policy1 item
- Companies Where the Company Holds ≥10%1 item
- Shareholders with Potential Conflict of Interest1 item
- Relationships Among Major Shareholders1 item
- Shareholders' Agreement1 item
- Shareholding Diagram (Group Structure)2 items
- Income Structure3 items
- Product / Service Characteristics2 items
- Research & Development6 items
- Assets Used in the Business4 items
- Marketing Policy & Competition3 items
- Procurement of Products & Services2 items
- Projects Under Construction1 item
- Debentures & Bills of Exchange1 item
- Convertible Securities2 items
Corporate Information
Company Name
Chase Asia Public Company Limited
Telephone
02 855 8222
Website
www.chase.co.th
contactcenter@chase.co.th
Dividend Policy
Dividend Policy
The Company has a policy to pay dividend to the shareholders at the rate not less than 40 percent of the net profit from the separate financial statements less corporate income tax and legal reserve as required by law and its articles of association. Such dividend rate is subject to change, depending on financial position, operating results, financial liquidity, cash flows and working capital requirements for management and business expansion of the Group, economic conditions, contractual conditions, restrictions and obligations, as well as other factors relating to the Group’s operations, as the Board of Directors and/or shareholders of the Company may deem reasonable.
The annual dividend payment must be approved by the Shareholders’ Meeting, except for interim dividend, which may be approved by the Board of Directors from time to time as justified by the Group’s profit, in which case, such dividend payment shall be reported to the next Shareholders’ Meeting for information.
Historical Dividend Payments
| This Year | Last Year | 2 Years Ago | Metric | Description | Remark |
|---|---|---|---|---|---|
| 0 | 0.04 | 0.07 | Net profit per share (Baht : Share) | Net profit per share (baht : share) | Basic earnings per share |
| 0.01 | 0 | 0 | Dividend per share (Baht : Share) | Dividend per share (baht : share) | |
| 0 | 0 | 0 | Dividend stock ratio (Number of original shares: dividend shares) | Ratio of stock dividend payment (existing share : stock dividend) | |
| 0 | 0 | 0 | Dividend share value per share (Baht : Share) | Value of stock dividend per share (baht : share) | |
| 0.01 | 0 | 0 | Total dividend payment value (Baht : Share) | Total dividend payment (baht : share) | |
| 40 | 0 | 0 | Dividend payout ratio to net profit (%) | Dividend payout ratio compared to net profit (%) | Dividend payout ratio compared to net profit calculated using 2024 net profit figures derived from the Separate Financial Statements. |
Business Strategies Overview
Chairman's Message
The year 2025 marked another period in which Chase Asia Public Company Limited had to navigate a business landscape defined by multi-dimensional challenges. These stemmed from volatile economic structures and household debt levels that remained persistently high. It is undeniable that these factors directly impacted the debt-servicing capacity of the general public and the Company’s broader debtor base.
Amidst these challenges, the Company remained steadfast in its commitment to a prudent and cautious business approach. In 2025, we adjusted our investment strategies to align with the current climate, implementing rigorous selection criteria for Non performing asset acquisitions. This balanced approach was designed to maintain cash flow stability and ensure the quality of our asset portfolio remained at an optimal level.
Beyond prudent portfolio management, the Company continues to prioritize efficient debt resolution. We aim to create opportunities for debtors to settle their obligations in line with our corporate vision. We hope to serve as a small but vital gear that helps drive stability within the national economy, ultimately empowering our debtors to regain their financial standing.
Simultaneously, the Group continues to focus on sustainable growth. We have tangibly integrated Environmental, Social, and Governance (ESG) principles into our business strategy to create long-term value for all stakeholders.
On behalf of the Board of Directors and the management team, I would like to express my sincere gratitude to our shareholders, business partners, executives, staff, and all stakeholders for your continued trust and confidence in our operations. We pledge to dedicate our utmost efforts to managing the business, driving stable growth, and delivering sustainable returns to all stakeholders.
Vision
To be a full-service debt management center by counseling, knowledge and discipline for debt management towards debt resolution.
Objectives
To build reliable, honest and attentive services to debtors and concerned parties;
To manage debts professionally on a full-scale service as required by applicable rules and regulations to ensure the utmost satisfaction of trading partners; To regularly improve the quality of services and personnel to build personnel specializing in providing the services with new ideas for sustainable growth;
To create an opportunity for debtors to start a new life;
To manage and supervise business by “taking into account concerned parties” on the basis of corporate governance, ethics and morality, along with social and environmental responsibility towards the economic and social sustainability.
Goals
The Group is committed to developing the organization to become a leader in the full-service debt management for financial institutions subject to the business operations on the basis of corporate governance and the code of ethics to drive the Company’s business towards sustainability, and to be number one in counseling for debtors.
Business Strategies
Asset Management Maintenance and Strategic Growth
The Group remains steadfast in its commitment to maintaining and driving the growth of the Asset Management segment, with a particular focus on the unsecured non-performing loan (NPL) portfolio, an area where the Group possesses extensive long-term expertise and experience. Our strategy emphasizes a highly selective acquisition approach to ensure that each investment generates high-quality, sustainable returns. Following the acquisition of NPL portfolios, the Group accelerates the debt restructuring and settlement processes. This dual-purpose strategy aims to alleviate the financial burden of debtors while simultaneously strengthening the quality and resilience of the Group's overall asset portfolio.
Digital Transformation and Process Optimization
The Group continues to prioritize organizational development through digital transformation. Recently, we launched and further developed the "ARMA" application and the Collection Management System, both of which serve as core strategic tools supporting both front-office and back-office operations. We are committed to the continuous enhancement of these platforms to deliver superior service quality. Beyond these primary tools, the Group focuses on digitalizing ancillary workflows and integrating automation into our processes to maximize operational efficiency and achieve optimal results.
Human Capital Development and Empowerment
The Group is dedicated to the continuous development, training, and empowerment of our personnel. By fostering outstanding capabilities and unlocking the full potential of our workforce, we build a robust organizational foundation that drives sustainable momentum and long-term growth for the Group.
Commitment to Sustainable Growth
The Group is committed to driving sustainable organizational growth by enhancing business operations rooted in responsibility toward all stakeholders across economic, social, and environmental (ESG) dimensions. Our ultimate goal is to contribute to the resolution of non-performing debt issues within the Thai financial system, promoting overall economic stability.
Material Changes & Developments
Material Changes & Developments
| Year | Description |
|---|---|
| 1,998 | Khun Pracha Chaisuwan and the management team founded the Company with a registered capital of Baht 1.0 million to provide the debt collection and recovery services. |
| 2,001 | The Company opened the first branch office located in Nakhon Ratchasima Province. |
| 2,003 | RWAY was founded with a registered capital of Baht 1.0 million, which was subsequently increased to Baht 10 million to acquire non-performing accounts receivable |
| 2,005 | The Company was engaged by American Expressway Co., Ltd. to provide the debt collection and recovery services for the first year, which continues until now. |
| 2,012 |
|
| 2,015 | COURTS was acquired from the existing shareholders to carry on the loans business under Civil and Commercial Code |
| 2,020 | The Company acquired shares in RWAY, CFAM and COURTS from the existing shareholders as part of the Group’s shareholding restructuring to prepare for an initial public offering (IPO) and listing of the Company’s ordinary shares on the SET, thereby causing the Company to hold 100.0 percent of issued and paid-up shares in the subsidiaries |
| 2,021 | R Alliance Co., Ltd., a subsidiary of RS Public Company Limited, acquired 35.0 percent of issued and paid-up shares in the Company from the existing shareholders. |
| 2,022 |
|
| 2,023 |
|
| 2,024 |
|
| 2,025 |
|
Use of Proceeds from Securities Offerings
Is There Money Raised from a Securities Offering Still to Report On?
No
Commitments Made in the Registration Statement
Are There Commitments or Conditions from an Offering or Listing?
No
Group Operating-Structure Policy
Description
The Company operates as the parents company of the group, with its core business centered on providing comprehensive debt collection and litigation services for both financial institutions and private corporate clients.
The Company’s primary objective is to manage and ensure debt recovery in accordance with the terms specified by
its clients. The Company exercises control over its operations through the following key subsidiaries:
Resolution Way Co., Ltd.: Primarily engaged in the acquisition and management of non-performing loans from financial and non-financial institutions. It also provides personal loan services under the supervision of the Bank of Thailand.
CF Asia Asset Management Co., Ltd.: Specializes in the management of both secured and unsecured non-performing loans (NPLs) acquired under the Emergency Decree on Asset Management Companies.
Courts Megastore (Thailand) Co., Ltd.: Manages a personal loan portfolio under the Civil and Commercial Code.
Currently, Resolution Way Co., Ltd and Courts Megastore (Thailand) Co., Ltd focuses exclusively on debt collection and recovery from its existing customer base, having ceased the approval of new credit facilities since December 31, 2022.
Companies Where the Company Holds ≥10%
Companies (≥10% Holding)
| Company Name | Address | Province | Zip Code | Telephone | Business Type | Security Type | Shares | Paid-up Shares |
|---|---|---|---|---|---|---|---|---|
| Resolution Way Co., Ltd. | 34/6, Moo 1, Chaengwattana Road, Khlong Kluea Subdistrict, Pak Kret District | Nonthaburi | 11120 | 02 821 1055 | Personal loan business under BOT’s regulation, and acceptance of transfer of non-performing assets from financial and non-financial institutions | Common shares | 520,042 | 520,042 |
| CF Asia Asset Management Co., Ltd. | 34/6, Moo 1, Chaengwattana Road, Khlong Kluea Subdistrict, Pak Kret District | Nonthaburi | 11120 | 02 826 5377 | Management of non-performing assets from acceptance of transfer of non-performing assets under the Emergency Decree on Asset Management Company | Common shares | 170,489 | 170,489 |
| Courts Megastore (Thailand) Co., Ltd. | 34/6, Moo 1, Chaengwattana Road, Khlong Kluea Subdistrict, Pak Kret District | Nonthaburi | 11120 | 02 857 5188 | Loan business under the Civil and Commercial Code | Common shares | 3,670,585 | 3,670,585 |
Income Structure
Product / Service Income
| Category | Description | This Year | This Year % | Last Year | Last Year % | 2 Years Ago | 2 Years Ago % |
|---|---|---|---|---|---|---|---|
| Total revenue from operations | Total revenue from operations | 737,467.85 | 100 | 816,482.04 | 100 | 681,460.48 | 100 |
| Debt collection service | 194,481.81 | 26.37 | 192,217.24 | 23.54 | 185,647.94 | 27.24 | |
| Asset management of transferred non-performing loans (NPLs) | 514,523.16 | 69.77 | 586,506.57 | 71.83 | 464,917.09 | 68.22 | |
| Other income | 2,082.43 | 0.28 | 3,530.26 | 0.43 | 5,241.74 | 0.77 | |
| Lending services | 26,380.46 | 3.58 | 34,227.97 | 4.19 | 25,653.71 | 3.76 | |
| Other | Other | 0 | 0 | 0 | 0 | 0 | 0 |
Export Income
| Category | Description | This Year | This Year % | Last Year | Last Year % | 2 Years Ago | 2 Years Ago % |
|---|---|---|---|---|---|---|---|
| Total revenue | Total revenue from operations | 737,467.85 | 100 | 816,482.04 | 100 | 681,460.48 | 100 |
| Domestic | Domestic | 737,467.85 | 100 | 816,482.04 | 100 | 681,460.48 | 100 |
| International | International | 0 | 0 | 0 | 0 | 0 | 0 |
Other Income
| Operating Other Income | Non-Operating Other Income | Share of Profit |
|---|---|---|
| 1710 · As of year: 1953.35 · Description: Total other income · As of yesteryear: 2743.28 · As of year before yesteryear: 2478.48 · 1711 · As of year: 0.0 · Description: Other income from operations · As of yesteryear: 0.0 · As of year before yesteryear: 0.0 | 1712 · As of year: 1953.35 · Description: Other income not from operations · As of yesteryear: 2743.28 · As of year before yesteryear: 2478.48 | 1713 · As of year: 0.0 · Description: Share of profit · As of yesteryear: 0.0 · As of year before yesteryear: 0.0 |
Product / Service Characteristics
Business Type
3115
Business Groups
| Business Group | Description | |||||||||||||||||||||||||||||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Debt Collection and Recovery Services | The Group has provided debt collection and recovery services to financial institutions (commercial banks), non-financial institutions, and private companies (collectively, the “Employers”) to follow up and demand debtors to pay their debts under the conditions as designated by the Employers. There are a variety of debts which the Group provides the debt collection and recovery services to financial institutions, such as, personal loan debts, credit card debts, etc. The majority of debts which the Company provides the debt collection and recovery services to the Employers, which are non-financial institutions, involve such service providers whose customers owed the service charges. Other than the debt collection and recovery services, the Group also provides litigation services on a full-scale basis to the Employers, which include service of notices, filing of lawsuits against debtors, and legal execution of court judgments against debtors, etc. As of December 31, 2025, the Company has clients which are financial institutions, their affiliated companies, and private companies. In order to ensure that the Group’s debt collection services comply with its rules and regulations, and the Bank of Thailand’s rules and regulations, the Company has a policy to have all debt collectors undergo training from the Debt Collection Business to Financial Institution Association, or related knowledge training hosted by the Group. Moreover, all debt collectors of the Group are also registered with the Lawyers Council of Thailand. The Group earns remuneration from the debt collection and recovery services at the rates agreed upon with the Employers, depending on the debt complications, based on the percentage of the sums collected and recovered by the Group, and remuneration from the litigation services in the form of professional fees per case. The following table demonstrates revenue from the debt collection and recovery services for the years ended December 31, 2023, 2024 and 2025, by type of services:
Debt Collection and Recovery Services From its past experience and reputation well recognized in the industry, the Company has been regularly approached by financial institutions and the Employers which are non-financial institutions. The Company considers accepting jobs by taking into account the business category and nature of products of the Employers, including the Company’s sufficient personnel. Upon receipt of contact by an Employer, and should the Company consider accepting the job, the Company would enter into an engagement agreement with the Employer to obtain debtors’ information from the Employer accordingly. Once the Company receives debtors’ information from the Employer, the Company would then thoroughly check the completeness of such information before entering the same into the Company’s debt collection and management system. The Company would sort the list of debtors into groups and assign its debt collectors to contact debtors according to such information provided by the Employer within 48 hours or in accordance with the conditions and policy of the Employer. The Company’s staff would use such information provided by the Employer, and their experience and expertise in data search to contact debtors. In the event where any debtor cannot be contacted, the Company would inform the Employer accordingly. Should the engagement agreement include the litigation services, the Company would use the court proceedings as the next step. However, should the engagement agreement not cover the litigation services, the Company would suggest the Employer to grant approval for the Company to represent it in the legal proceedings for the purpose of debt collection for the Employer. Prior to proceeding with the debt collection, the debt collector in charge will inform the debtor every time of his/her full name according to the identification card, the Company’s name, and the Employer’s name, as well as the debts under the Company’s assignment for the debt collection, and the debt collector will always verify the debtor’s identity before proceeding with the debt collection, e.g., asking and confirming the debtor’s full name, etc. The debt collectors are obliged to contact, negotiate, offer counselling and solution with debtors in order for them to settle their debts owed to the Employers. The Company has a policy for its staff to contact debtors based on such information provided by the Employers only via the Company’s telephone system, which will record all telephone conversation between the Company’s staff and debtors, and keep such data as agreed upon with the Employers for submission to the Employers for review of the Company’s operations at the Employers’ request. In addition, the Company will submit a summary of the debt collection by the Company according to the timeline as designated by each Employer. Debtors will make payments to the Employer directly only through the channels designated by the Employer, since the Company has no policy to receive any debt payments for further remittance to the Employer at a later date. The Employer will send a daily report on the debt payments to the Company to confirm debtors’ payment status for the Company to obtain up-to-date debtors’ payment status in order to avoid any repeated collection and prevent any complaints. | |||||||||||||||||||||||||||||||||||||||||||||||
| Management of Non-Performing Assets | The Group operates the business of management of non-performing assets mostly transferred from financial institutions in Thailand, both secured and unsecured, through its two subsidiaries, namely CFAM which is licensed by the Bank of Thailand to operate the business under the Emergency Decree on Asset Management Company, and RWAY. CFAM focuses on acquiring non-performing accounts receivable from sellers which are financial institutions under the regulation of the Bank of Thailand, while RWAY focuses on acquiring non-performing accounts receivable from sellers which are not financial institutions under the regulation of the Bank of Thailand. The Group accepts transfer of non-performing assets, both secured and unsecured, from financial and nonfinancial institutions, for debt collection and recovery, by way of counseling for debt resolution to debtors and/or counseling for debt restructuring, using its experience in the debt collection and recovery services to manage nonperforming assets to the maximum benefits. Procurement of Non-Performing Assets The Group always monitors information and searches for opportunities to acquire non-performing assets from financial and non-financial institutions (the “Sellers”). Generally, the Sellers would offer non-performing assets for sale by way of auction or direct negotiation with asset management companies. Should the Company find any non-performing assets offered by any Seller for auction or sale attractive, the Group would express its intention to attend such auction or enter into negotiation and execute a confidentiality agreement with the Seller to obtain such documents regarding information of non-performing assets offered for sale so as to proceed with a due diligence investigation and data analysis to determine a reasonable purchase price. In the course of the due diligence investigation, the Group’s Portfolio Analysis Department would essentially consider the justification of the rate of return on investment and risks thereof from key factors, namely debts by right of claim, debtors’ historical backgrounds, cash flow forecast expected to be derived by the Group from all debtors, litigation status, types and quality of collateral, etc. Should the non-performing assets offered for sale be secured non-performing assets, the Portfolio Analysis Department would consider the collateral values in order to determine a purchase price before submission to the authorized person for further approval of such acquisition. In general, the Group will pay for such assets acquired from financial institutions on the date of the Group’s execution of the relevant purchase and sale agreements for non-performing assets, provided that the payment terms shall be as agreed upon between the Group and the Seller. The following table demonstrates loans to non-performing assets – net per the Group’s consolidated financial statements by type of loans as of December 31, 2023, 2024 and 2025:
Management of Non-Performing Assets Once the Group has entered into the purchase and sale agreements for non-performing assets from financial institutions, the Group would obtain debtors’ information and then thoroughly check the completeness of such information before entering the same into the Group’s debt collection and management system. The Group will contact debtors, guarantors and mortgagors and send them a notice of assignment of claims informing the debtors of the Group’s status as creditor by virtue of the assignment of claims from the Seller, the debts, contact and payment channels of the Group. In the event where the Group cannot contact any debtors, the Group may consider using the court proceedings to take legal actions against such debtors. Once the Group has contacted the debtors, the Group will provide them with counseling and solutions, and may consider granting discounts to the debtors, taking into account their payment records, income, careers, collaterals, etc., for submission to the authorized person for further consideration and approval. However, should any debtor fail to negotiate or settle the debts, the Group may take the legal proceedings for further actions. Payment Channels At present, the Group uses the Bill Payment System to receive payments from debtors, whereby the Group’s debtors will receive payment form in order to scan barcode or QR Code to make payments at (1) payment service points at all Lotus’s branches; (2) Mobile Banking Application of all banks; or (3) payment orders or money transfer from the debtors’ bank accounts to the Group’s bank account via any branch of commercial banks or ATM machines. | |||||||||||||||||||||||||||||||||||||||||||||||
| Other business - Lending Service | In the past, the Group (COURTS and RWAY) engages in the personal loan business under the regulation of the Bank of Thailand and the CCC Loans business to non-performing debtors, both debtors of the Group (CFAM and RWAY) and non-performing debtors of other financial institutions, under the product name Hope Loan (the “Hope Loan”), with the main purpose of affording non-performing debtors with debt-serviceability potential an opportunity to resolve their debt problems on the basis of debt consolidation, reduction and resolution. In this regard, the Company will provide advice to debtors to resolve their debt problems by extending Hope Loan to non-performing debtors (both such debts of CFAM and RWAY and those of other financial institutions) whom the Company believes that they are capable of repaying the loans. The Company will check the applicants’ payment records of other loans from the Credit Bureau reports, consider their debt-serviceability, monthly installment plan, and in case an applicant is a new external customer without any payment records with the Group, the applicant must be accompanied by a co-borrower and/or collateral, etc. Should the Company consider approving the applicant’s application, the Company will prepare only a cheque payable to the order of the original financial institution in order to close the original debt account on the date the Company and the debtor execute the loan agreement. COURTS started to operate the Hope Loan business since 2017 and RWAY discontinued extending Hope Loan since 2020. However, the Company considered the risks of debtors’ debt-serviceability from Hope Loan, and resolved to suspend Hope Loan extension, provided that such loans would be approved only for debtors who had already consulted with the Group and been in the course of negotiation with the existing creditors, and the consideration and approval of new loans were discontinued since December 31, 2022. For accounts receivable in the loan business currently with outstanding balances, the Group would continue to monitor all debtors’ debt repayments under the agreed upon terms and conditions accordingly. Even though COURTS and RWAY have discontinued the consideration and approval of new loans since December 31, 2022, the Group initially continues to earn interest income from Hope Loan due to monitoring of debt repayments by debtors whom COURTS and RWAY previously extended the loans under the agreed upon terms and conditions. Moreover, RWAY plans to use proceeds from the Hope Loan debt collection to bid for nonperforming assets portfolio accordingly. | |||||||||||||||||||||||||||||||||||||||||||||||
Research & Development
Has R&D Policy (Y/N)
No
R&D Cost — Description
The Company emphasizes and promotes the integration of innovation and advanced technology to enhance its competitive advantage and effectively address the diverse needs of all stakeholders. This commitment is firmly grounded in a framework of social and environmental responsibility.
In 2024 and 2025, the Group’s research and innovation development activities were carried out entirely by internal personnel; therefore, no expenses were incurred for the acquisition of external technologies.
R&D Cost — Label
Research and development (R&D) expenses over the past 3 years (Million Baht)
R&D Cost — This Year
0.0
R&D Cost — Last Year
0.0
R&D Cost — 2 Years Ago
5006806.63
Assets Used in the Business
Permanent Assets — Description
As at December 31, 2025, the Group’s fixed assets used in its business operations based on the net book value less accumulated depreciation in the consolidated financial statements amounted Baht 390.4 million or representing 10.0% of total assets. Fixed assets mainly used in the Group’s business operations per the consolidated financial statements comprise land, buildings and building improvements, office equipment.
Moreover, as at December 31, 2025, the Group’s net right-of-use assets amounted to Baht 5.2 million or representing 0.1% of total assets. The majority of the Group’s right-of-use assets include buildings and office equipment used by the Group in its business operations.
As at December 31, 2025, the Company and its subsidiaries had a total of 15 head and branch offices, with the Group’s head office located at Chaengwattana Road, Nonthaburi. The details of the head and branch offices of the Company and its subsidiaries are described below.
Head/Branch Office | Company | Scope of Services |
| Company | Debt Collection, Litigation and Enforcement |
| Company | Debt Collection and Enforcement |
| Company | Debt Collection and Enforcement |
| Company | Debt Collection and Enforcement |
| Company | Debt Collection and Enforcement |
| Company | Debt Collection and Enforcement |
| Company | Debt Collection and Enforcement |
| Company | Debt Collection and Enforcement |
| Company | Debt Collection and Enforcement |
| Company | Debt Collection and Enforcement |
| Company | Debt Collection and Enforcement |
| Company | Debt Collection |
| RWAY | Management of NPL and Loan Services |
| CFAM | Management of NPL |
| COURTS | Loan Services(1) |
Remark: (1) The Group plans to discontinue the consideration and approval of new loans since December 31, 2022. However, for accounts receivable in the loan business currently with outstanding balances, the Group would continue to monitor all debtors’ debt repayments under the agreed upon terms and conditions accordingly.
Intangible Assets — Description
As at December 31, 2025, the Group’s intangible assets used in its business operations based on the net book value less accumulated amortization in the consolidated financial statements amounted Baht 6.9 million or representing 0.18% of total assets include program and software licensing fees.
Has Subsidiaries Investment Policy (Y/N)
Yes
Subsidiaries Investment Policy — Description
The Group focuses on investing in businesses that support its core operations and generate synergies. Governance is exercised through the appointment of representatives as directors or executives in proportion to shareholding to ensure operations align with Group policies. The Group closely monitors the accurate, complete, and timely disclosure of financial information. Furthermore, significant transactions require prior approval from the Board of Directors or shareholders to protect investment interests and maintain confidence through a robust internal control system.
Full Policy can be found via the link: https://www.chase.co.th/storage/content/cg/corporate-policies/20260304-chase-investment-policy-th.pdf
Marketing Policy & Competition
Reporting Mode
3117
Marketing Policy (Overall)
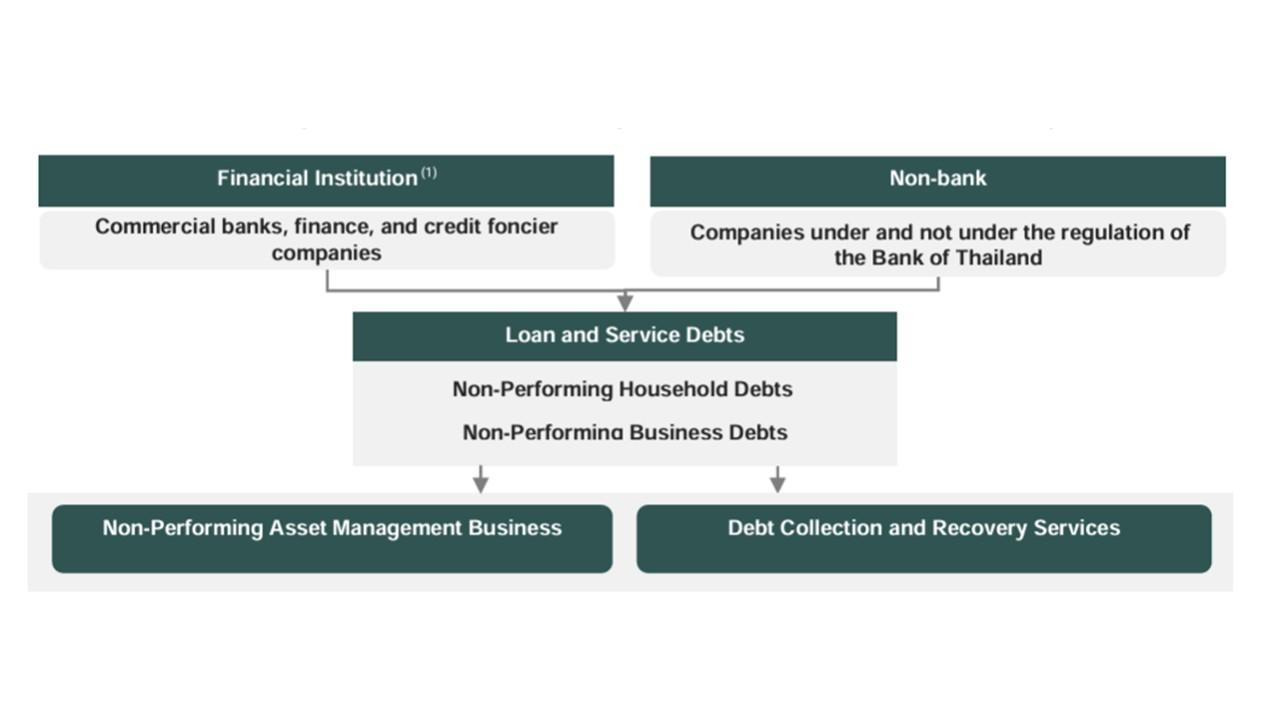
Asset management companies play a key role in the national economic development, as a mechanism for nonperforming debt resolution, with the duty to acquire or accept transfer of non-performing secured and unsecured assets for management, debt restructuring and negotiations under such measures as set out by law. The disposal or transfer of such responsibility for non-performing asset management to asset management companies which particularly specialize in non-performing asset development will help reduce the volume of non-performing debts in the Thai financial institution system, and also reduce the financial institutions’ non-performing debt forecast, which serves as a good solution to financial restructuring for financial institutions, enables them to focus on lending transactions towards the credit system development, and strengthen Thailand’s economy to grow with quality and sustainability. However, each of financial institutions or non-bank service providers manages their non-performing debts differently as follows:
An internal unit is delegated to proceed with negotiations and provide the debt collection and recovery services in respect of delinquent accounts and non-performing debts, which may incur high costs and lack efficiency should the personnel in charge have no direct expertise in the debt collection. Moreover, as long as financial institutions or non-bank service providers continue to hold non-performing debts, they would be required to establish provisions/allowances as required by applicable rules and regulations.
A third party is engaged to proceed with negotiation, and provide the debt collection and recovery services, including litigation services, which would help improve the efficiency in the non-performing debt management, as a popular alternative particularly among financial institutions, e.g., commercial banks and personal loan business, etc. However, given that the Employers continue to hold non-performing debts, they would be required to establish provisions/allowances as required by applicable rules and regulations.
Non-performing debts are sold at a discounted price to asset management companies, which serves as an alternative to afford the lenders versatility to control their non-performing loans at an appropriate level, reduce costs and expenses in the debt collection, and alleviate their burden to establish provisions/allowances as required by applicable rules and regulations. At the same time, such asset management companies would be required to manage and assume the risks of collection of such debts acquired, although there are opportunities to generate profits from successful debt collection.
The establishment of a Joint Venture Asset Management Company (JV AMC) is a model for managing distressed assets under the regulations and conditions prescribed by the Bank of Thailand (BOT). It serves as an effective tool for resolving non-performing loans (NPLs) within the financial institution system. Under this model, financial institutions and asset management companies co-invest to transfer distressed assets for management. This approach allows financial institutions to immediately reduce their NPL ratios and alleviate the burden of provisioning in accordance with BOT regulations, while maintaining the opportunity to receive future returns through profit-sharing from the joint venture. Furthermore, operations under the JV structure align with the BOT’s policy focusing on sustainable debt restructuring. By leveraging the specialized expertise of asset management companies, the JV can evaluate and assist debtors with greater flexibility and speed. This not only maintains the stability of the financial institution system but also increases the chances for debtors to resume economic activities under prudent supervision.
Industry & Competition (Overall)
Economic Overview
According to the National Economic and Social Development Council (NESDC), the Thai economy in 2025 grew by 2.4%, compared to 2.9% growth in 2024. This performance was primarily supported by expansions in private and government consumption, as well as an increase in investment. In the fourth quarter of 2025, the economy grew by 2.5%, accelerating from the 1.2% growth recorded in the third quarter. Regarding household debt in Thailand, the latest report from the Bank of Thailand shows a continued decline in the household debt-to-GDP ratio to 86.8%, down from a peak of 95.5% in 2024, stable with the previous quarter. While this figure remained stable quarter-over-quarter, it continues to exceed regional benchmarks. Consequently, high leverage levels remain a primary headwind, potentially restricting the recovery of domestic demand. To address the persistent challenge of high household debt and sluggish income recovery, the Bank of Thailand has launched the "Clear Debt Fast, Move Forward" initiative in collaboration with the Ministry of Finance, the Thai Bankers' Association, Sukhumvit Asset Management (SAM), and the National Credit Bureau (NCB). Officially starting on January 5, 2026, this strategic program aims to unlock financial freedom for over 3 million retail debtors, representing 64% of all individuals currently in default. By streamlining debt resolution, the project seeks to remove a major barrier to domestic spending and ensure the Thai economy remains on a sustainable path forward.
Target Customer Groups and Key Markets
The Group focuses on financial institutions and large private corporations as its primary markets, categorized by business type as follows:
Debt Collection Service Business: Primary clients include financial institutions and non-bank lenders (Non-banks), such as personal loan and credit card providers.
Asset Management Business: Regarding asset sellers, the target group includes financial and non-bank institutions seeking to manage Non-Performing Loan (NPL) portfolios, both secured and unsecured.
Target Debtor Group: Focuses on household debt, such as personal loan, credit card, and hire-purchase agreement debtors, areas where the Company possesses expertise in counseling and debt restructuring.
Demand & Supply Overview
Demand: The primary driver is the need for financial and non-bank institutions to efficiently manage their balance sheets. By offloading NPLs, institutions reduce their provisioning burden and increase capital allocation potential, enabling them to expand new lending and support overall economic recovery. Balancing this demand and supply is a crucial factor in the Company’s asset management strategy.
Supply: The volume of distressed assets in the financial and non-bank systems tends to fluctuate with economic conditions. During economic slowdowns, NPL volumes typically rise. However, supply entering the market may temporarily slow down due to Bank of Thailand (BoT) assistance measures, which reduce the outflow of NPLs to auctions to support debt restructuring within the banking system.
Factors Affecting Growth Rates
Macroeconomic conditions represent a primary factor significantly influencing the company’s growth trajectory both for Asset Management Business and Debt Collection services, particularly in a landscape where household income expansion has slowed or remains uneven. This environment directly impacts liquidity and debt-servicing capacity, as consumers must prioritize essential daily living expenses. Such circumstances align with Thailand’s household debt-to-GDP ratio, which remains persistently high, acting as a key catalyst for the rising trend of Non-Performing Loans (NPLs) within the financial institution system.
However, while the volume of debt in the system increases, the supply of distressed assets released by financial institutions may partially slow down due to various debt moratorium measures. This situation can lead to intensified price competition, potentially resulting in higher asset acquisition costs and/or adversely affecting the internal rate of return (IRR) and the payback period.
Furthermore, changes in government regulations and supervisory policies, including relief measures from the Bank of Thailand—such as the "Khun Soo Rao Chuay" (You Fight, We Help) program or various debt suspension schemes—serve as mechanisms to maintain overall economic stability. Nevertheless, from an operational standpoint, these measures may impact the efficiency and timeframe of the company’s debt collection during certain periods. These collective factors represent significant challenges that require rigorous management to sustain growth targets. Concurrently, the company faces strategic risks from aggressive competition within the Asset Management Company (AMC) market as the number of players increases. If the supply of debt offered by financial institutions does not meet market demand, bidding costs will rise, directly impacting profitability and capital recovery timelines.
Industry Competition Landscape
Debt Collection
Competition in this sector is characterized by operational efficiency and regulatory compliance standards. Primary clients, largely financial institutions, place the highest priority on strict adherence to the Debt Collection Act and the Bank of Thailand’s regulations. Currently, the market is highly fragmented with numerous medium and large-scale operators, leading to intense price competition regarding service fees. However, the Company maintains its competitive edge by upholding rigorous operational standards that consistently align with regulatory requirements, which remains a key differentiator for institutional clients.
Asset Management Business
Competition in this business involves aggressive bidding for distressed assets, particularly in the current economic climate where the volume of NPLs in the financial system is rising. The market faces challenges from the entry of new players, including Joint Venture Asset Management Companies (JV AMCs) formed between financial institutions and established AMCs, which benefit from superior databases and lower costs of funds. Success in this competitive landscape depends not only on the bid price but also on the accuracy of asset valuation and the ability to minimize operational costs.
According to the latest statistics from the Bank of Thailand as of the fourth quarter of 2025, there were 86 registered asset management companies with total system-wide assets amounting to THB 301,163 million. Within this landscape, CF Asia Asset Management Company Limited (the Company’s subsidiary) held total assets of THB 1,725 million, representing a 0.6% market share of the total assets within the registered AMC system.
Regarding the major players listed on the Stock Exchange of Thailand - who significantly influence industry pricing and operational standards - the market remains concentrated among five key companies (including the Group). Each participant maintains a distinct competitive strategy based on their expertise in specific asset classes:
Secured NPL Specialists
Unsecured Retail NPL Specialists
Corporate NPL Specialists
As of December 31, 2025, the Group’s net loans to non-performing assets amounted to THB 2,851 million. When analyzed quantitatively against the five major listed peers, the Group held a 3% market share based on the total asset value of this group.
Competitive Advantages of the Company
The Company believes that it has the following competitive advantages:
The Group is one of the leading full-service debt management service providers.
The Group believes that as one of the leading full-service debt management service providers, it will help facilitates its trading partners, both financial and non-financial institutions. The Group can provide the collection services of debts which have not yet been classified as non-performing debts to lessen trading partners’ burdens to follow up in order to fully contribute time for their core business operations. Should such debts change the status as nonperforming debts, the Group may accept transfer of such debts for further management in order to shorten the duration and procedures for searching and/or getting to know debtors, which will render the management transition to proceed seamlessly. The Group’s business operations which cover both the debt collection and recovery services for trading partners, and the debt collection services from credit portfolios for non-performing assets will enable the Group to utilize its resources efficiently.
The Group has long-time experience and expertise in the industry.
The Group has over 20 years of experience in the debt negotiation and recovery services, and as such, the Company has staff who specializes in the debt collection steps and procedures, and is well aware of and understand applicable rules and regulations. In addition, the Group’s over 20 years of experience have brought about good and long-standing relationships with financial institutions, and understanding of credit portfolios for nonperforming assets sold by each of the financial institutions, and as such, the Group is capable of reasonably determining purchase prices and selecting appropriate portfolios for management.
The performance of the Group’s top management is well recognized and accepted in the non-performing asset management industry, thanks to their long-time experience in the field through multiple financial crises, namely from the 1997 Asian financial crisis (Tom Yam Kung crisis), the 2008 subprime mortgage crisis (Hamburger crisis), up to the financial crisis caused by the coronavirus disease 2019 (“COVID-19”) pandemic. They are knowledgeable and understand the business cycle very well and capable of properly adapting to changing situations and economic conditions.
Moreover, Khun Pracha Chaisuwan, the Group’s founder, is the President of the Debt Collection Business to Financial Institution Association since 2022, and continues to resume such position, and in 2025, Khun Pracha has also been appointed to be the President of the Thailand Asset Management Company Association. This reflects the trust in Khun Pracha’s experience, knowledge and expertise from members in both the debt collection business to financial institution and the Thailand asset management companies, under the vision towards driving, promoting and supporting the operations of entrepreneurs in Thailand so as to enhance the efficiency in the debt collection and asset management business operations, create a network for other companies in the same industry, encourage consultations with the relevant regulatory agencies, and support the overall financial market development in Thailand.
The Group has a number of personnel with legal knowledge and expertise in the litigation and legal execution.
The Group has litigation and legal execution personnel with expertise in the law enforcement for debt collection, which enable the Group to pursue non-performing debtors requiring the legal procedure. Such ability allows the Group to accept a more variety of jobs as it can recover debts in every status in the debt collection and recovery services. Moreover, the debt collection services for non-performing debtors requiring the legal procedure would be charged at a higher service rate than debts in other status. As for the management of non-performing assets, such ability for law enforcement in the efficient debt collection also enables the Group to recover more debts accordingly.
Procurement of Products & Services
Reporting Mode
3117
Procurement (Overall)
Non-Performing Loan (NPL) Acquisition: The Group continuously monitors market trends and identifies opportunities to acquire non-performing loans (NPLs) from both financial institutions and non-bank entities. Generally, sellers divest NPLs through competitive auctions or direct negotiations. To ensure prudent investment, the Portfolio Analysis Department conducts rigorous due diligence to evaluate the appropriateness of expected returns, risk profiles, and projected cash flows before determining a final bid price.
Debt Collection Service Procurement: The Company consistently earns the trust of clients, leading to ongoing service inquiries and the proactive pursuit of new business opportunities. In selecting engagements, we prioritize the client’s industry type, the specific nature of their products, and our internal workforce capacity and expertise. This selective approach ensures we maintain the highest standards of service quality and operational excellence.
Supply Chain Management: The Procurement Department oversees the sourcing of office equipment and services. Our operations are guided by a Supplier Code of Conduct to ensure that all business partners operate with transparency, uphold human rights, and maintain environmental responsibility. We conduct ESG (Environmental, Social, and Governance) risk assessments for our suppliers and require all key vendors to formally sign and acknowledge their compliance with our Code of Conduct.
Projects Under Construction
Has Projects Under Construction (Y/N)
No
Debentures & Bills of Exchange
Has Debentures (Y/N)
No
Convertible Securities
Has Convertible Securities (Y/N)
Yes
Convertible Securities
| Security Name | Issued Date | Exercise Date(s) | Maturity Date | Exercise Price | Exercise Ratio | Allotted Shares | Convertible Shares | Unconverted Shares | Remaining Convertible | Notification Period | Description |
|---|---|---|---|---|---|---|---|---|---|---|---|
| Warrants to Purchase the Company’s Ordinary Shares Series 1 | 2024-06-06 | On the last Business Day of June and December between 9.00 and 15.00 hrs., throughout the Term of the Warrants. The first exercise date is on 30 December 2024 and the last exercise date is on 4 June 2027 | 2027-06-04 | 0.5 | 1.000:1.000 | 198,544,180 | 198,544,180 | 197,528,857 | 197,528,857 | Between 9.00 and 15.00 hrs. on the Business Days within 5 Business Days prior to each exercise date Last Exercise Date which requires the declaration of the intention to exercise Warrants within 15 days prior to the Last Exercise Date | The Company has disclosed the documents related to CHASE-W1, namely
1) Information Memorandum: Description, Conditions and Major Characteristics of CHASE-W1;
(2) Terms and Conditions Governing the Rights and Obligations of the Issuer and Holders of CHASE-W1; and
(3) Notification Form of Exercise of CHASE-W1,
on the Company’s website at https://www.chase.co.th/en/investor-relations/downloads/warrant-information under Information on CHASE-W1.
|